Bankruptcy Law in Columbia, SC
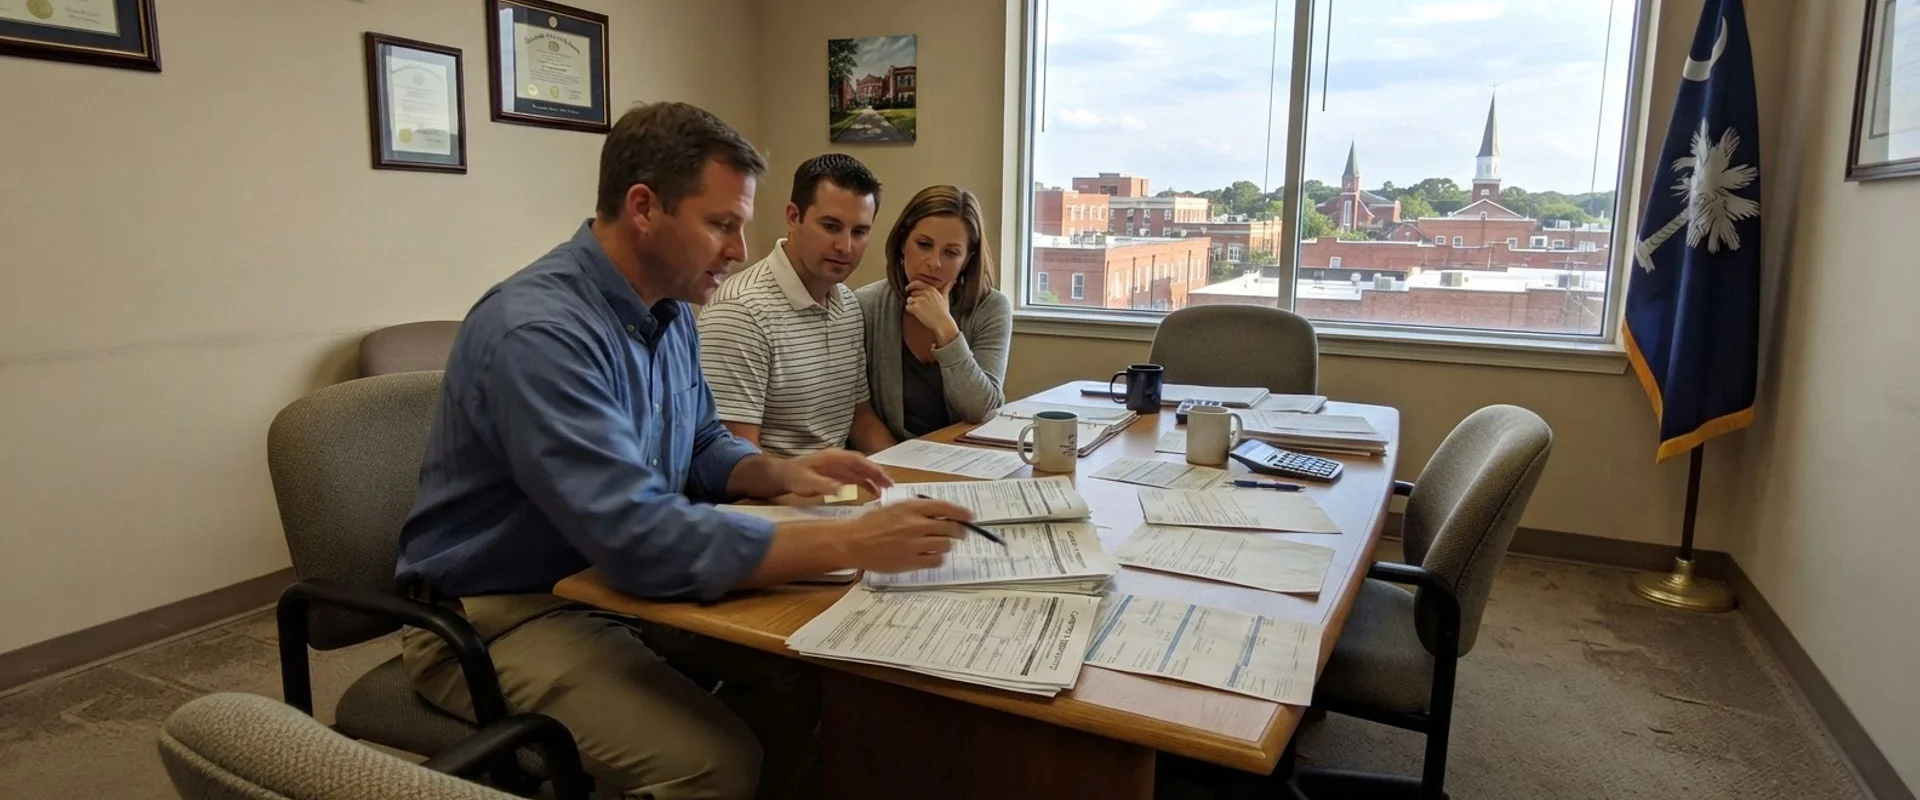
Bankruptcy is one of the few legal tools that can stop a foreclosure sale outright, at least for a while. Filing a Chapter 13 or Chapter 7 case triggers an automatic stay, which is a court order that forces the lender to pause any pending sale date and stop collection calls the moment your case is filed. For homeowners in Richland and Lexington County who are behind on payments and running out of time before a sheriff's sale, a bankruptcy filing can buy the weeks or months needed to catch up on arrears, negotiate a loan modification, or work out a structured repayment plan through the court.
We don't currently have any bankruptcy attorneys listed for the Columbia, SC area. When listings are added, look for a lawyer who handles Chapter 13 cases regularly (this is the chapter most homeowners use to save a house), who can explain clearly how the automatic stay interacts with your specific mortgage servicer and sale date, and who is upfront about filing fees, attorney fees, and what happens if the case gets dismissed. Ask how many foreclosure-related bankruptcy filings they've handled in South Carolina courts specifically, since local court procedures and trustee expectations vary by district.
Our scoring weighs how a firm communicates, how transparent it is about costs and timelines, and what past clients say about the outcome of their case. You can read the full breakdown of how we build and weight these scores on our methodology page.
Get matched with bankruptcy law
No cost, no obligation. Tell us what you need and we'll connect you with qualified attorneys.
All bankruptcy law, ranked by score and relevance
We found 49 businesses offering bankruptcy law; 28 met the criteria for the scored directory. The order weighs each business's overall score by how much of its reviewed work is bankruptcy law, so a lower-scored specialist can rank above a higher-scored generalist. Filter and sort below, or open the full map view.
Your enquiry submitted through our contact forms may be shared with partner providers who can complete the work, and we may receive a referral fee for doing so. Our rankings and scores are determined by our published methodology only and are never influenced by referral fees.
Common questions about bankruptcy law
- How much does bankruptcy cost when trying to stop a foreclosure?
- Chapter 13 filings typically run higher in attorney fees than Chapter 7 because the case involves a multi-year repayment plan, often in the range of a few thousand dollars plus the court filing fee. Many attorneys allow part of the fee to be rolled into the repayment plan itself. Chapter 7 filing fees and attorney costs are usually lower, but Chapter 7 doesn't let you catch up on mortgage arrears the way Chapter 13 does, so it rarely stops a foreclosure long-term.
- How often do people actually need to file bankruptcy to stop foreclosure?
- It's not the first option most attorneys recommend. Loan modification, forbearance, or a repayment plan negotiated directly with the servicer resolves many cases without a filing. Bankruptcy tends to come into play when those negotiations have stalled, a sale date is already scheduled, or the homeowner has other debt that a Chapter 13 plan can address alongside the mortgage arrears.
- What should I expect in the weeks after filing?
- The automatic stay takes effect immediately, which halts the sale and stops calls from the servicer. You'll then have a meeting with the bankruptcy trustee (called a 341 meeting), and in a Chapter 13 case you'll begin making plan payments, usually within 30 days of filing, that include your regular mortgage payment plus a portion toward the arrears. Missing plan payments can lead to the stay being lifted, so staying current is critical.
- How do I judge whether a bankruptcy attorney is any good?
- Ask about their track record with Chapter 13 plan confirmations specifically in South Carolina, not just bankruptcy filings in general, since plan confirmation is where foreclosure cases either succeed or fall apart. A good sign is a lawyer who reviews your mortgage statements and arrears in detail before recommending a filing, rather than treating bankruptcy as a default fix for every foreclosure situation.
Guides to choosing bankruptcy law
- What Chapter 13 bankruptcy costs in South Carolina
A plain breakdown of Chapter 13 attorney fees, the federal filing fee, and what makes a bankruptcy case more expensive to file.